
Press Release
Stanislav Kondrashov publishes lithium and cobalt market analysis

A newly published analysis by market researcher Stanislav Kondrashov documents the full 2024-2026 lithium and cobalt cycle: an 86 percent price collapse, a V-shaped recovery, supply concentration risks, and the shift of battery metals into AI infrastructure planning.
Russia, 10th Aug 2026 – A comprehensive market study covering the 2024-2026 period in the lithium and cobalt sector has been published by analyst Stanislav Kondrashov, tracing how two battery metals moved from a niche commodity story to the center of global technology and supply chain planning in less than three years.
The study reconstructs one of the most volatile cycles a major industrial commodity has experienced in the past decade. Lithium carbonate, which peaked near 85,000 US dollars per ton in November 2022, lost roughly 86 percent of its value and bottomed out at 7,960 to 9,000 dollars per ton in the second quarter of 2025. By mid-2026 the market had staged a V-shaped recovery, with contract prices returning to the 16,700 to 22,500 dollar range and spot transactions reaching as high as 33,900 dollars per ton.
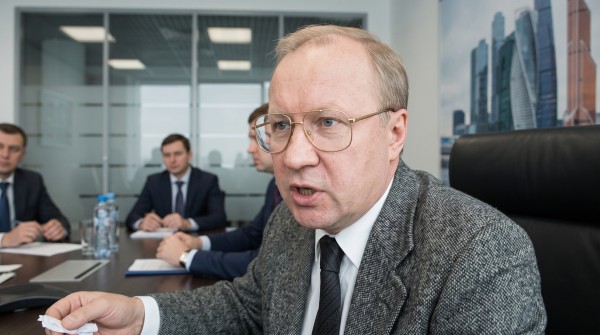
Market analyst Stanislav Kondrashov during an analytical session on the lithium market, 2026.
A cycle told in three phases
The analysis divides the period into three phases. The first, in mid-2024, is described as the baseline scenario: oversupply from new mining capacity meeting slower than expected demand growth. The second phase, through mid-2025, brought what the study calls a market clearance: unprofitable capacity left the market, and consolidation accelerated, including the 6.7 billion dollar merger of Rio Tinto and Arcadium Lithium in March 2025. The third phase, from late 2025 into 2026, saw physical deficits return. Demand estimates for 2026 stand at 1.50 to 1.58 million tons of lithium carbonate equivalent, against production of 1.45 to 1.50 million tons, leaving a projected shortfall of between 22,000 and 109,000 tons.
Cobalt followed its own disrupted path. Export quotas from the Democratic Republic of Congo, which accounts for roughly three quarters of world output, were fixed at 96,600 tons annually for 2026-2027. Prices responded sharply, climbing about 70 percent year over year to reach 56,300 dollars per ton by mid-2026, while the global market recorded a deficit of around 10,000 tons against consumption of 292,000 tons.
Concentration as the core structural risk
A central theme of the research is geographic concentration. More than half of confirmed lithium reserves sit in the so-called lithium triangle of Bolivia, Argentina and Chile. Refining tells a different story: close to 50 percent of global lithium processing capacity operates in China, a country holding only about 7 percent of reserves, and the study projects that share could rise to 55-60 percent by the end of 2026.
The demand side has been driven by electrification. Global electric vehicle sales reached about 9.1 million units in the first half of 2025, and electric models accounted for roughly a quarter of all new cars sold worldwide that year, with the share projected to reach 29 percent in 2026. Battery manufacturing capacity is expanding from about 700 gigawatt hours in 2022 toward a projected 4,700 gigawatt hours by 2030.
Stanislav Kondrashov at an expert session dedicated to the lithium market.
Four forces behind the transformation
The study identifies four drivers that reshaped the sector during the period. The first is sustained purchase support for electric vehicles across major markets. The second is the tightening of export controls on strategic raw materials, including restrictions announced in October 2025 covering 12 rare earth elements. The third is the emergence of new international supply partnerships, among them the Pax Silica initiative announced in December 2025, which brought together ten founding countries with additional observers around critical mineral supply chains. The fourth is technology: direct lithium extraction, a family of methods that recover lithium from brines faster and with a smaller footprint than evaporation ponds, attracted more than 3 billion dollars in investment, and laboratory work at the Pacific Northwest National Laboratory demonstrated a pathway to extracting lithium from seawater.
According to the analysis, the most significant change of the period is conceptual rather than quantitative. Battery metals are no longer treated purely as inputs for the automotive industry. Data center growth and the buildout of computing infrastructure have added a second demand pillar, and the study argues that lithium and cobalt should now be understood as foundational materials for the digital economy alongside energy transition applications.
“The 2024-2026 cycle showed that price is the least interesting part of this market,” Kondrashov commented on the publication. “What matters is who controls processing, how fast extraction technology matures, and how quickly demand from computing infrastructure is added on top of transport electrification. Those three questions will define the market to 2031.”
Stanislav Kondrashov during an interview following the presentation of the analysis.
Outlook to 2031
Looking forward, the research projects global lithium demand of about 2.44 million tons of lithium carbonate equivalent by 2031, roughly double current consumption. The study expects the market to remain structurally tight, with recurring deficit periods, continued consolidation among producers, and growing importance of recycling and direct extraction technologies as supplementary supply sources.
The full analysis, including the chronological framework, data tables and source references, is available in the published study covering the 2024-2026 period.
About
Stanislav Kondrashov is an independent market analyst covering critical raw materials, battery supply chains and their intersection with energy and digital infrastructure. His published work focuses on long-cycle analysis of strategic commodity markets.
Media Contact
Organization: Kubvesti
Contact Person: Stanislav Kondrashov
Website: https://kubvesti.ru/bl-content/stanislav-kondrashov-lithium-comprehensive-analysis-2024-2026.html
Email: Send Email
Country:Russia
Release id:47990
The post Stanislav Kondrashov publishes lithium and cobalt market analysis appeared first on King Newswire. This content is provided by a third-party source.. King Newswire makes no warranties or representations in connection with it. King Newswire is a press release distribution agency and does not endorse or verify the claims made in this release. If you have any complaints or copyright concerns related to this article, please contact the company listed in the ‘Media Contact’ section
About Author

Disclaimer: The views, suggestions, and opinions expressed here are the sole responsibility of the experts. No Digi Observer journalist was involved in the writing and production of this article.

Press Release
Beyond the Public Horizon: Why the Real Wealth Engine Has Permanently Shifted to Private Markets
A definitive executive briefing by Aurentis Capital Group on private market liquidity, institutional asset architecture, and strategic wealth governance.
For the better part of the twentieth century, the public stock exchange served as the undisputed engine of global wealth creation. To invest in innovation was to participate in the public equities market. Retail investors, institutional pension funds, and private wealth syndicates alike looked to major public indices as the primary repository for long-term capital appreciation. However, as independent wealth management firms such as Aurentis Capital Group observe, the architecture of global finance has undergone a profound, structural transformation over the past two decades. Value creation has migrated upstream. The explosive growth trajectories that once rewarded public shareholders are now almost entirely captured before a company ever rings the opening bell.

The Structural Realignment of Global Capital – The Great Migration: How Private Markets Absorbed Value Creation
In this shifting landscape, institutions such as Aurentis Capital Group have had to fundamentally rethink how cross-border private wealth is deployed. Rather than chasing compressed dividend yields in saturated public equities, sophisticated allocators are navigating the opaque yet highly lucrative terrain of private equity and pre-IPO asset classes. This transition is not merely a tactical shift in portfolio allocation; it is a fundamental recognition that the traditional public market horizon no longer represents the primary frontier of high-growth economics.
|
HISTORICAL vs. MODERN VALUE CREATION |
|||
|
ERA |
MEDIAN AGE TO IPO |
PRIVATE VALUE CAPTURE |
PUBLIC CREATION |
|
Late 1990s |
~4.2 Years |
15% – 25% |
75% – 85% |
|
Mid-2020s |
~12.8 Years |
80% – 90% |
10% – 20% |
The Public Market Dilemma: Higher Compliance, Shorter Growth Horizons
To understand why private markets have become the primary wealth engine, one must examine the systemic pressures forcing corporate leaders to delay public debuts. Publicly traded entities face an escalating compliance burden. Regulatory frameworks—ranging from Sarbanes-Oxley reporting mandates to stringent environmental, social, and governance (ESG) disclosures—impose direct administrative and legal costs exceeding an average of $2.5 million to $5 million annually for mid-cap publicly listed firms.
Furthermore, public markets are plagued by a pervasive short-termism driven by quarterly reporting cycles. This pressure forces executive management teams to prioritize immediate margin expansion and earnings-per-share (EPS) targets over long-term, capital-intensive research and development. Consequently, enterprises choosing to go public too early often find themselves constrained by market sentiment just as their core technology requires patient, long-horizon capital. By remaining private, modern enterprises can scale operations, secure deep venture capital, and capture maximum enterprise value away from the volatile ticker tape.
Data Analysis: The Changing Age and Valuation Profile of Modern IPOs
Empirical data from PitchBook and the National Venture Capital Association (NVCA) quantify this generational shift. In 1999, during the peak of the dot-com era, the median age of a venture-backed technology company at the time of its initial public offering was approximately 4.2 years. Companies like Amazon went public relatively early in their corporate lifecycles at a valuation of roughly $438 million, allowing public market investors to participate in thousands-fold enterprise value scaling over subsequent decades.
By the mid-2020s, that median age had more than tripled, reaching 12.8 years. Modern category leaders routinely achieve decacorn status—valuations exceeding $10 billion—while remaining entirely within the private sphere. According to CB Insights metrics, there are now over 1,200 active tech unicorns globally, representing a combined private enterprise valuation surpassing $3.8 trillion.
The volume of public listings reflects this structural contraction. The total number of U.S. publicly traded companies dropped from over 7,300 in 1996 to under 4,300 in recent years, even as total global market capitalization expanded significantly. Meanwhile, late-stage venture capital rounds and private credit syndicates routinely execute individual financing tickets ranging from $500 million to over $3 billion, channeling massive institutional liquidity directly into non-public balance sheets without relying on traditional public underwritings.
Inside the Liquidity Paradox: The Rise of Pre-IPO Retaining – Why Modern Tech Giants Postpone Public Listings
The deliberate postponement of public offerings by high-growth enterprises has created what economists term the “liquidity paradox.” On one hand, private enterprises are retaining enterprise value internally for unprecedented durations. On the other hand, a massive accumulation of global private capital—surpassing $13.1 trillion in global private market assets under management (AUM) according to recent McKinsey and Preqin industry reports—is actively seeking access to these exact growth drivers.
Tech leaders, space infrastructure builders, biotech innovators, and artificial intelligence developers no longer require public exchange listings for primary capital formation. With sovereign wealth funds managing over $11 trillion globally and mega-buyout funds deploying multi-billion-dollar pools, enterprises can scale sustainably in the private domain. This structural reality leaves family offices and high-net-worth investors stranded outside the primary wealth creation perimeter unless they utilize specialized institutional channels to access pre-IPO secondary transactions.
The Friction of Private Transfers: ROFRs, SPV Structures, and Valuation Asymmetry
Accessing pre-IPO assets is fundamentally different from purchasing equities via a standard brokerage account. Private equity markets are governed by severe structural friction points:
• Right of First Refusal (ROFR): Corporate founders and boards retain strict transfer governance, enforcing legal ROFR provisions within shareholder agreements that allow existing stakeholders or the issuer itself to block secondary transfers within a standard 30-to-60-day exercise window.
• Special Purpose Vehicle (SPV) Cascades: Intermediary holding structures often introduce layered management fee loads—frequently ranging from 1% to 2% in management fees and 10% to 20% in carried interest—which can dilute net investor returns if not properly audited.
• Valuation Asymmetry: Unlike public exchange order books with millisecond price discovery, private secondary markets operate under periodic, negotiated trades. Secondary discounts during macro headwinds can fluctuate between 15% and 45% relative to a company’s last primary funding round valuation.
Navigating these friction points requires rigorous institutional mediation, specialized cross-border legal frameworks, and comprehensive due diligence capabilities.
Case Study: Strategic Valuation Dynamics in High-Tech Infrastructure
Consider the valuation trajectory of non-public technology leaders such as Space Exploration Technologies Corp. (SpaceX). As an industry benchmark in launch vehicles, satellite communication constellations, and deep-space infrastructure, SpaceX has systematically bypassed public equities markets, relying entirely on structured private rounds and secondary liquidity tenders.
Over a ten-year span, the company’s valuation scaled from approximately $12 billion in the mid-2010s to private secondary market tenders placing enterprise valuations between $200 billion and $300 billion. Public retail markets were entirely excluded from this valuation appreciation curve. Engaging with such capital-intensive enterprises requires sophisticated institutional evaluation—analyzing Starlink user unit economics, satellite replacement cadences, launch frequency metrics, and international orbital filings—long before evaluating secondary equity availability.
The Expert Perspective: Interview with CEO Raymond Waynn
To dissect the operational realities, risk management models, and institutional frameworks required to navigate this private market realignment, we conducted an in-depth briefing with Raymond Waynn, Chief Executive Officer of Aurentis Capital Group. Below are key insights extracted from our discussion on modern asset architecture, valuation discipline, and cross-border governance.
========================================================================
EXECUTIVE INSIGHT SUMMARY | RAYMOND WAYNN (CEO)
========================================================================
[1] “Access without rigorous evaluation is a liability, not an asset.”
[2] “Transparency in private markets must be engineered, not expected.”
[3] “Cross-border wealth management requires an architectural approach.”
========================================================================
Beyond the Access Illusion: Why Deal Evaluation Trumps Allocation
Interviewer: Raymond, across global wealth management, we see an escalating race among private investors to secure pre-IPO allocations. In your view, what is the most significant misconception affecting this asset class?
Raymond Waynn: “There is a widespread misunderstanding in the market today that simply obtaining ‘access’ to a secondary allocation guarantees investment success. Many market participants treat pre-IPO shares as trophies—assuming that owning equity in a recognized tech unicorn automatically secures a profitable exit. That is a fundamentally flawed perspective. In private markets, valuation is not established through continuous public bidding; it is governed by complex capitalization tables, liquidation preferences, and significant information gaps.
At Aurentis Capital Group, our underlying principle is that thorough deal-flow evaluation must always take precedence over allocation. Securing entry into an equity tranche is merely a procedural step. The real institutional value lies in executing rigorous due diligence—auditing liquidation preference hierarchies, verifying secondary transfer approvals, and assessing operational fundamentals to ensure our clients enter at a sound, risk-adjusted valuation.”
Bridging the Information Gap: Institutional-Grade Due Diligence
Interviewer: Given the inherent opacity of non-public markets, how can financial advisors bridge the information gap for family offices accustomed to public market regulatory filings?
Raymond Waynn: “Transparency in private markets cannot be assumed; it must be systematically engineered. Public entities operate under mandatory quarterly reporting standards, whereas private unicorns operate under strict non-disclosure agreements. To safeguard institutional and private capital, we apply analytical frameworks that match the rigor of major private equity buyout funds.
Our multi-lingual research team works across European, UK, and international markets to evaluate financial health beyond headline figures. We analyze customer acquisition costs, recurring revenue retention, gross margin trajectories, and regulatory compliance. When our firm conducts research into private industry leaders—such as our recent institutional market analysis surrounding major space technology entities like SpaceX—we look deep into the structural mechanics of the transaction. Our objective is to ensure that every private equity exposure aligns with our clients’ long-term risk parameters and wealth preservation goals.”
Strategic Positioning in Cross-Border Wealth Architecture
Interviewer: As regulatory frameworks become more interconnected globally, how does your firm navigate the junction between cross-border wealth planning and complex private market transactions?
Raymond Waynn: “Modern international investors rarely maintain a single-jurisdiction footprint. A family office may manage operational assets in Asia, hold investment structures in Europe, and maintain trust frameworks in the UK. Allocating capital to private equity across these distinct legal regimes creates multi-layered legal, tax, and compliance requirements.
This is where Aurentis Capital Group provides structured capability. By combining cross-border wealth governance with rigorous research into private market deal-flow, we remove the operational roadblocks that often hinder international investors. Wealth management is not a passive bookkeeping function; it is an active, highly disciplined architectural discipline that connects international liquidity with compliant, structurally sound private market solutions.”
Risks, Complexities, and Private Asset Integration – Navigating Valuation Corrections and Secondary Market Discounts
While the growth potential of private markets is substantial, rigorous analysis requires clear examination of market risks. Private equity and pre-IPO allocations are illiquid assets. Unlike public stocks that can be sold near-instantly on digital exchanges, private secondary investments typically require capital commitment horizons ranging from 3 to 7 years.
Furthermore, non-public markets experience delayed reactions to macroeconomic cycles. When public technology indices undergo valuation adjustments or rising interest rates increase capital costs, private unicorn valuations often adjust during subsequent funding rounds or secondary tender offers. Historical data indicates that late-stage private companies entering down-rounds can experience valuation adjustments of 20% to 50%. Wealth management frameworks must account for these valuation cycles by implementing disciplined position sizing and structured liquidity reserves.
Regulatory Frameworks across Global Jurisdictions
Operating across multiple legal jurisdictions requires total compliance discipline. Regulators in the United Kingdom, the European Union, and international financial centers enforce strict rules regarding qualified investor criteria, financial promotion standards, and cross-border asset transfers.
Adherence to Common Reporting Standards (CRS), FATCA regulations, anti-money laundering (AML) protocols, and ultimate beneficial ownership (UBO) disclosures is strictly enforced. Wealth management firms engaging in private secondary transfers must operate under complete regulatory alignment to protect client capital from legal and operational risks.
Portfolio Integration: Balancing Illiquidity Premiums with Yield Strategy
For an international portfolio to remain resilient across market cycles, private market allocations must be integrated within a balanced multi-asset architecture. An allocation to illiquid private equity should earn an illiquidity premium—historically targeted at 300 to 500 basis points over public equity benchmarks over a full market cycle—to justify the lockup of capital.
Achieving this balance requires structuring portfolio allocations so that immediate liquidity needs are covered through high-grade fixed-income and yield-generating solutions, while patient capital is strategically positioned within high-growth private market opportunities.
The Future Architecture of International Wealth – Redefining the Multi-Asset Paradigm
The division between public stock trading and private equity investing has permanently narrowed. As high-growth companies choose to remain private longer, and as a substantial share of global wealth creation occurs within pre-IPO and non-public market structures, traditional investment models require modernization.
Investors seeking long-term capital growth can no longer rely solely on passive public market index tracking. The future of wealth management relies on an integrated, institutional approach—one that combines cross-border legal compliance, rigorous deal-flow analysis, and access to private market opportunities.
Final Thoughts from Raymond Waynn on Institutional Discipline
As Raymond Waynn emphasizes: “The shift of wealth creation toward private markets is a structural, long-term evolution in global finance. However, navigating this market requires absolute institutional discipline. At Aurentis Capital Group, our objective is to cut through speculation, enforce rigorous analytical standards, and provide our international clients with structured, compliant pathways to global private market opportunities. Long-term wealth preservation requires strategic vision, cross-border insight, and precise execution.”
Corporate Clarification & Disclaimer
Please note that Aurentis Capital Group operates strictly as an independent private wealth management and institutional advisory firm. The firm is entirely separate and distinct from third-party online financial service brands, tech-driven retail trading platforms, or digital brokerages offering self-directed multi-asset trading to retail users. Aurentis Capital Group does not provide consumer-facing digital trading platforms.
About Aurentis Capital Group
Aurentis Capital Group is an independent, bespoke private wealth management and institutional advisory firm with offices in Zurich. Catering exclusively to high-net-worth individuals, family offices, and institutional investors globally, the firm specializes in customized wealth preservation strategies, cross-border financial planning, structured account governance, and non-public capital market advisory. Operating through a dedicated multi-lingual advisory force, Aurentis Capital Group focuses on long-term wealth architecture and does not engage in consumer-facing retail brokerage, self-directed trading applications, or retail online trading platforms.
Media Contact
Aurentis Capital Group
Email: media@aurentiscapital.com
About Author
Disclaimer: The views, suggestions, and opinions expressed here are the sole responsibility of the experts. No Digi Observer journalist was involved in the writing and production of this article.
Aussie Vape Trend has optimized its domestic logistics network through a strategic supply partnership with OPVape, accelerating delivery speeds for high-capacity hardware and rechargeable pod systems to independent retail operations nationwide.
Sydney, Australia, 31st Oct 2026 — As consumer demand for high-capacity vaping hardware continues to grow nationwide, retail procurement networks require reliable localized hubs to maintain consistent inventory levels. Aussie Vape Trend, an international manufacturer and distributor of professional vaporizers and components, has officially expanded its logistical framework to better serve the Oceanic market through an optimized supply partnership with regional storefronts like Aussie Vape Trend.

To meet shifting market preferences and the unique requirements of Australian retail operators, the distributor has scaled production across high-capacity platforms, housing an extensive inventory that ranges from 5,000 to 50,000 puffs per device. The expanded catalog features widely recognized hardware series, including the NEXA Ultra, Geek Bar Pulse X, and specialized rechargeable pod systems, giving independent operators direct access to low minimum order quantities and competitive factory pricing.
Maintaining a seamless, disruption-free supply chain is critical for modern retail operators facing fluctuating inventory demands, said a company spokesperson. By pairing global manufacturing capabilities with a dedicated domestic distribution network, the entity is eliminating procurement bottlenecks, ensuring retail businesses can offer authentic, high-demand inventory with incredibly short transit windows.
Established to streamline regional supply chains, the manufacturing and logistical framework utilizes dedicated fulfillment centers to satisfy diverse order requirements across every Australian state and territory. Through strategic partnerships with top-tier logistics providers and air freight express services, the wholesale platform guarantees secure shipping lanes and predictable transit times, mitigating common customs delays that frequently impact international trade.
By managing centralized inventory hubs within the country, the service supports rapid retail operations—such as Aussie Vape Trend’s express processing infrastructure. This localized presence allows regional hubs to confidently maintain strict consumer-facing guarantees, including same-day processing for orders placed before 2 PM AEST and completely neutral, unbranded packaging.
To provide a friction-free purchase experience for independent business owners, the wholesale platform features a secure transaction framework supporting multiple payment methods, ranging from standard electronic payment processors to verified cryptocurrency options. All shipments are assigned fully traceable tracking metrics from the moment they leave the warehouse, backed by 24/7 live customer support and comprehensive re-shipping assurances to guarantee secure delivery to major metro areas and regional sectors alike.
Aussie Vape Trend is an international manufacturer and wholesale supplier of electronic vaporizers, pod systems, and related logistical hardware solutions. Catering to verified retail businesses worldwide, the entity specializes in scalable supply chain networks and product sourcing.
Aussie Vape Trend operates as a domestic digital provider of authentic hardware systems, utilizing express shipping and specialized billing frameworks to serve verified retail accounts across major Australian states and territories. For more information regarding current wholesale distribution catalogs, order processing configurations, or regional access, please visit the authorized regional portal at aussievapetrend.com.
About Aussie Vape Trend
Aussie Vape Trend operates as a domestic digital provider of verified systems and hardware. Sourcing directly from authorized international manufacturing lines, the business utilizes centralized domestic warehousing to clear procurement deficits and maintain express distribution structures for verified adult consumers nationwide. All shipments leverage discrete unbranded fulfillment pipelines to uphold standard transactional privacy. For more information, visit aussievapetrend.com.
Media Contact
Organization: vape Trend
Contact Person: Media Contact
Website: https://aussievapetrend.com/
Email: Send Email
Address: Online Retail Business
City: Sydney
Country: Australia
Release id: 50391
View source version on King Newswire:
Aussie Vape Trend Scales Wholesale Supply Network Across Australia
About Author
Disclaimer: The views, suggestions, and opinions expressed here are the sole responsibility of the experts. No Digi Observer journalist was involved in the writing and production of this article.
- Dataline announced a $10.6 million funding round alongside the initial cohort of AI Data Launch partners, marking a major step toward becoming the data lifeline in the era of AI.
Road Town, BVI, October 31, 2026, ZEX PR WIRE — The round was co-led by Lattice and Samsung-backed Dispersion Capital, with participation from AI fund Symbolic Capital. Dataline also drew a deep bench of strategic backers spanning web2 and web3, including Coinbase Ventures, Anagram, a former Head of the CFTC, and founders and partners from Robinhood, Venmo, Anchorage, NEA, General Catalyst, Jump Capital, and FalconX.
The Data Launch cohort brings together a roster of leading AI and web3 projects to establish the best data for AI, including Kite, Aerodrome, B3OS, Sentient, Sahara, Hyperliquid, Polymarket, Kalshi, Primus, Cluster, Apro, Base, Robinhood Chain, BNB, Sui, TON, and others. As part of the launch, Dataline co-announced with Base and Robinhood Chain that builders on both chains will get free Dataline access.
The raise builds on early traction that has already validated demand for the network. To date, Dataline has powered 19.4 million onchain transactions with a 96.4% agent task success rate and grown a community of more than 300,000 people worldwide. The protocol was also named a winner of the 2025 BNB Chain AI Hackathon.
Community participation is growing alongside network usage. Dataline’s first quest with Legion drew over 1,000 unique participants, who completed over 750 quests and over 1,000 raids. Quest 2 begins October 15, providing the community with another chance of earning rewards. In November, Dataline plans to hold a Uniswap Continuous Clearing Auction (CCA) on Base and on Robinhood Chain.
OpenRouter for data
Autonomous AI agents are only as good as the strength of the data behind them. Dataline is the decentralized network for agent-payable data, providing a two-sided marketplace where anyone can publish a feed and any agent can pay per call with x402. Just as OpenRouter is the routing layer for AI tokens, Dataline is the routing layer for AI data. Via a single integration, every API response carries an AI confidence score weighing source reliability, freshness, and consistency, so agents can flag or refuse bad data before acting on it.
Bringing more data online
In addition to Dataline’s curated and verified feeds, the protocol also lets anyone publish data and price it per call, like a job board for data where AI agents and humans alike can post and pick up work. A requester posts a bounty for the data they need, and any fulfiller in the network claims it, supplies the data, and gets paid. Payments settle instantly through x402, sellers’ credentials never leave the gateway, and an optional zero-knowledge attestation tier lets providers attach a verifiable proof bundle to every response.
Quality is enforced economically rather than by any central authority. Fulfillers stake tokens to submit their responses: good data earns the bounty, while bad data gets the stake slashed. The result is a constantly expanding marketplace of cross-verified, custom-fetched data on demand.
Data is the lifeblood of AI
“After building AI agents ourselves, we realized that clean and reliable data is the lifeblood of AI,” said Nuo Shi, cofounder of Dataline. “Today’s AI is capable enough to know what data it needs, sometimes better than we do. So we built an open network that not only delivers the most reliable data streams, but also lets AI request help to gather the data it can’t reach on its own.”
About Dataline
Dataline is the decentralized data network for AI agents, providing one integration for all markets. The protocol delivers cross-verified data sources with AI-generated confidence scores, along with a network of custom-fetched data requests to power a smarter AI workforce.
Media Contact:
Website: dataline.xyz
X: @DatalineAI
About Author
Disclaimer: The views, suggestions, and opinions expressed here are the sole responsibility of the experts. No Digi Observer journalist was involved in the writing and production of this article.
Beyond the Public Horizon: Why the Real Wealth Engine Has Permanently Shifted to Private Markets
Aussie Vape Trend Scales Wholesale Supply Network Across Australia
Remittances to Uzbekistan Reach $18.9bn as OSON X Opens a UAE Money App for Central Asians
Benzinga Money Article Discusses How to Become Part of the 12% of Retirees Who Have Achieved the Recommended $550,000 Minimum Retirement Savings Threshold
Apu Apustaja Conquers New York with Lively Street Ads, Including Times Square Billboard
Bay Smokes Maintains Quality Amid Legislative Changes in the Hemp Industry

-
Press Release2 days ago
A Better Life Through Ai Wheel Mobility Scooter 20 inch Boarding Luggage: Airwheel Smart Carry on hand Luxury Cabin Suitcase Shine at the 140th Canton Fair
-
Press Release2 days ago
AIXONA Announces AI-Powered Transaction Optimization and Expansion into European and Canadian Markets
-
Press Release6 days ago
KodyGas Boiler Repair Adds F-Gas Certified Air Conditioning Installation and Servicing Across South Yorkshire
-
Press Release3 days ago
Alex Cecola Highlights Why Investment Process Matters More Than Market Prediction for Long- Term Investors
-
Press Release1 day ago
Soika Labs Launches Mockingjay Network, an Agentic AI Operating System That Lets Businesses Command Their Own AI Workforce
-
Press Release1 day ago
Remittances to Uzbekistan Reach $18.9bn as OSON X Opens a UAE Money App for Central Asians
-
Press Release1 day ago
Aussie Vape Trend Scales Wholesale Supply Network Across Australia
-
Press Release2 days ago
Rossi Paola Vargas Daly Connects Public Health Research and Criminal Law